 Kamil Askerkhanov
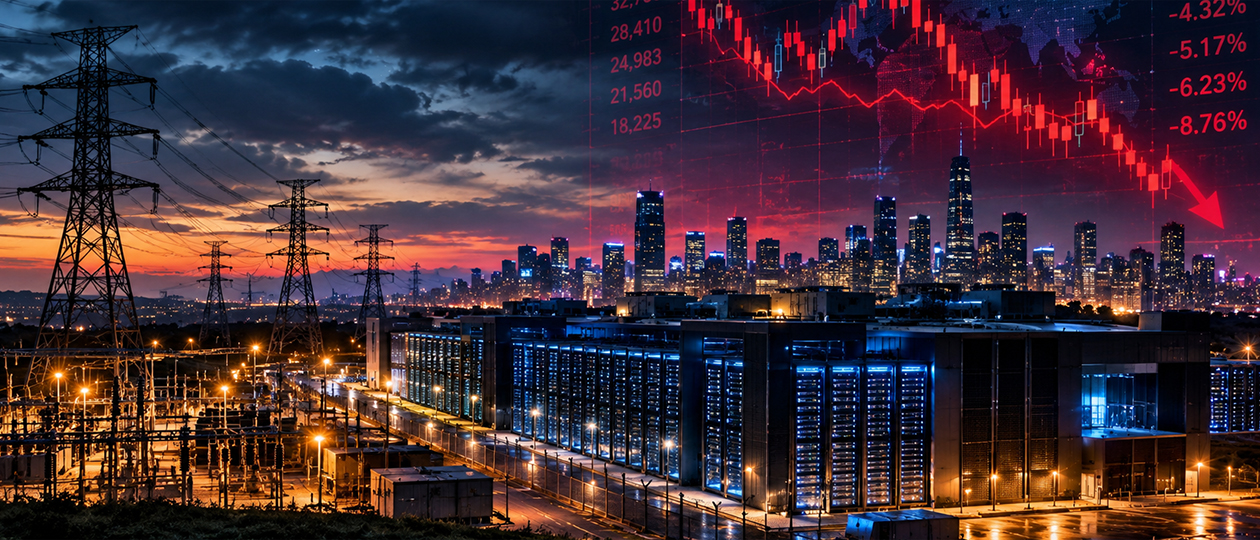
In recent remarks by Donald Trump and Larry Fink, the boss of BlackRock, there is a striking contradiction—one that, in my view, ought to be read in the context of a looming global financial and structural economic crisis.
Indeed, what is now taking shape increasingly resembles the sort of dynamics that preceded the Great Depression of 1929–33.
On October 14th Mr Fink warned that any slowdown in data-centre construction could push America into recession. In his telling, too large a share of current American growth already depends on capital spending on AI infrastructure.
A week later Mr Trump demanded that new giant data centres generate their own electricity, feed any surplus back into local grids and even pay something like dividends to the communities in which they are built.
Both statements deserve attention.
But the more interesting feature is that the head of the world’s largest investment firm is, in effect, warning the political authorities that they will bear responsibility if the investment cycle stalls. Put differently, he is identifying in advance the circumstances that could later be presented as the cause of a broader economic collapse.
This raises a suspicion: what we may be witnessing is the opening stage in a struggle to apportion blame for a future crisis. There is, for now, no proof of a co-ordinated script. But the very way Mr Fink has framed the matter is revealing.
Back in September, in an article entitled “Energy, money and security: the physical foundation of the new digital world”, I argued that, however virtual the new technological order may appear, it depends entirely on very material things: energy, computing infrastructure, raw materials and control over communications. It is around these resources, in fact, that the next system of economic power will be built.
So who is financing the construction of this infrastructure?
In September 2024 BlackRock, together with Microsoft and the Emirati firm MGX, announced an investment partnership with the potential to mobilise up to $100bn, including debt financing. Later the Kuwait Investment Authority, the country’s sovereign wealth fund, joined the venture. Then, in July this year, a consortium involving MGX and BlackRock completed the acquisition of Aligned Data Centers, valuing the business at roughly $40bn.
At the same time Saudi Arabia, through its sovereign wealth fund, PIF, and the company HUMAIN, has been investing heavily in computing infrastructure and partnerships with American technology firms.
The direction of capital flows is therefore plain enough. Vast financial resources accumulated by the oil monarchies over previous decades are beginning to finance the infrastructure of the new technological order.
Some of that money is going directly into the American economy; some into projects within the monarchies themselves that remain closely tied to American corporations.
And all this is taking place against a backdrop of a major war in the Middle East, the erosion of the region’s traditional security guarantees and mounting economic strains in the Gulf states.
I have previously suggested that the destabilisation now unfolding in the Middle East, together with the simultaneous channelling of Gulf capital into the American technology sector, may be linked. If so, what is at stake could be a vast redistribution of ownership extending well beyond the region itself.
To that hypothesis one should now add another element: the artificial-intelligence bubble.
An IMF report published in October highlights an especially curious financing structure. Just 14 large, interconnected transactions completed since 2023 account for roughly $300bn in equity investment, $650bn in debt financing and $1.4trn in future revenue commitments.
Firms are investing in one another, creating reciprocal demand, financing their partners and thereby helping to sustain the value of the entire structure.
Much of today’s valuation, in other words, rests on expectations of future returns whose scale still remains to be demonstrated.
This invites comparisons with earlier technology-driven investment cycles, especially the telecoms bubble of the early 2000s.
Then, immense sums were spent building fibre-optic infrastructure. After the crash, many firms went bust and financial investors suffered colossal losses. Yet the communications networks themselves remained and later passed into new hands.
Only this time, the stakes are considerably higher.
Imagine that the inflated technology bubble bursts just as a major debt crisis erupts—one that could easily evolve into a structural reordering of the world economy.
The shares of technology firms collapse. Debt obligations turn sour. Investment funds are forced to restructure assets. Foreign investors, including the Gulf monarchies, suffer heavy losses.
But the infrastructure built with their money remains. Power stations, electricity grids, data centres, land, communications systems and other physical assets do not disappear.
This leads to what may prove the central question: who will own all this after the crisis?
My own suspicion is that a significant share of this infrastructure may ultimately end up under state control, and that the transfer could take the form of direct or indirect nationalisation.
 Dmitri Drobnitsky
 Yuri Chekalin