 Kamil Askerkhanov
Signs of mounting stress in the global financial system are becoming increasingly apparent.
And recent events raise a familiar question: are we approaching a crisis whose consequences will be measured not merely in stock market losses, but in a massive redistribution of ownership?
On October 30, the Nasdaq fell 2.86%, the semiconductor index plunged 7.2%, and Intel shares lost almost 29% of their value in a single trading session.
But that proved to be only the beginning.
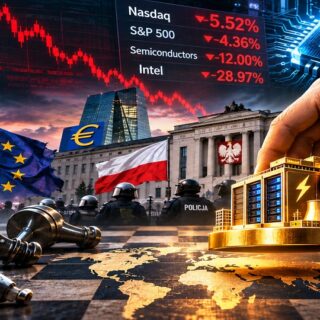
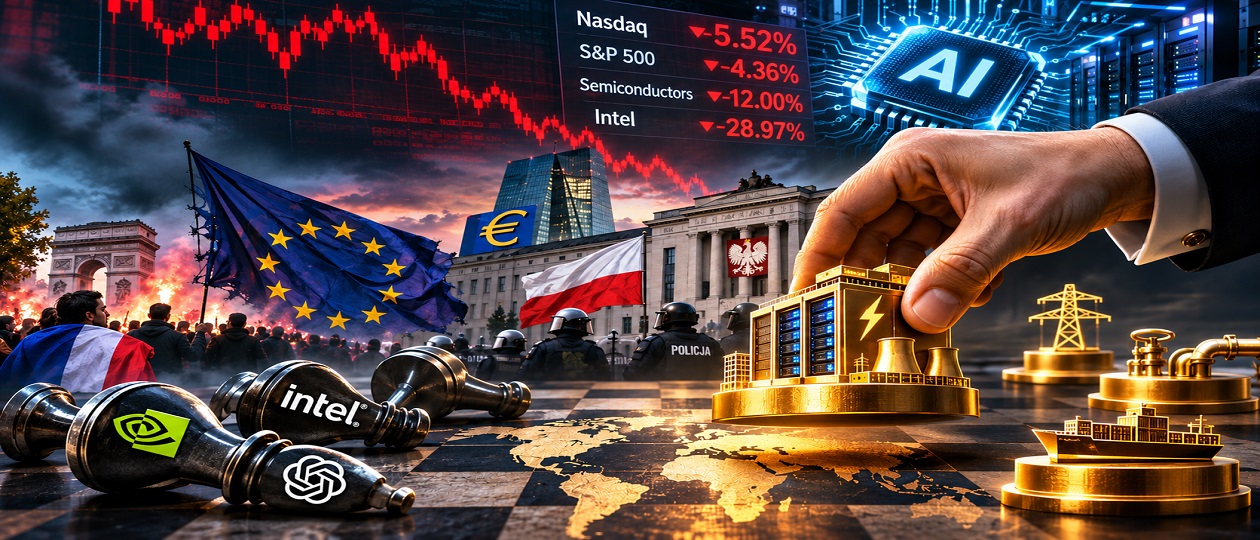
On November 5, the sell-off intensified dramatically: the Nasdaq tumbled 5.52%, the S&P 500 dropped 4.36%, and the Philadelphia Semiconductor Index shed more than 12%. The Nasdaq entered correction territory, falling more than 10% from its October peak.
As investors reassessed the prospects for artificial intelligence, semiconductor manufacturers, companies involved in building data centers, and energy producers counting on a surge in electricity demand all came under pressure. The sell-off also spread to cryptocurrencies, with Bitcoin falling to approximately $76,000 on November 5.
In China, the process began earlier. According to Reuters, the STAR 50 index, which tracks major technology and semiconductor companies, lost about 40% in less than four months. That represents roughly $480 billion in erased market capitalization.
Another particularly revealing development followed.
According to a Financial Times report published on October 30, OpenAI reduced its fundraising target from $30 billion to $20 billion while cutting its proposed valuation from $1.4 trillion to $1.25 trillion.
Investment entities from the United Arab Emirates, including the MGX fund, were reportedly among the potential major participants. These figures concern a proposed financing round, not a completed transaction.
Consider our longstanding hypothesis that enormous amounts of capital from around the world have been poured into artificial intelligence in recent years. The Gulf monarchies have been particularly active, investing both directly in technology companies and in the construction of vast computing infrastructure. They have been joined by institutional investors, major financial institutions, and funds managing long-term savings.
If the current sell-off develops into a systemic crisis, a question we have repeatedly raised will become unavoidable: who will bear the greatest losses, and who will ultimately own the data centers, energy infrastructure, and computing capacity built during the boom?
After all, a collapse in market capitalization does not make physical assets disappear. They may lose value, become unprofitable, or sit idle, but they continue to exist. And through bankruptcies, debt restructurings, foreclosures, and distressed asset sales, they can change hands.
This is how a financial crisis can turn into a massive redistribution of property.
Now consider Europe, where debt problems and political tensions are accumulating simultaneously.
On October 30, Fitch Ratings took the unscheduled step of revising the outlook on France’s sovereign credit rating from stable to negative while maintaining the rating itself at A+.
The agency pointed to deteriorating public finances, weak economic growth, a widening budget deficit, and the rising cost of servicing government debt. The French economy contracted by 0.1% in the third quarter. Government debt, which stood at 115.7% of GDP at the end of 2025, had already reached 119% by the end of the second quarter of 2026. Fitch forecasts that the figure could approach 124% by 2028.
According to the agency, France’s budget deficit could reach 5.5% of GDP in 2027, while debt-servicing costs are projected to rise from 2.5% of GDP in 2025 to 3.3% in 2028.
France is finding itself caught in an increasingly uncomfortable debt trap. Economic growth is weak, borrowing is expensive, and the political system is struggling to agree on spending cuts. Fitch specifically noted that political fragmentation and social tensions are obstructing efforts to put public finances on a sustainable footing.
And all this is happening in the eurozone’s second-largest economy.
But there is another factor to consider.
In recent months, European monetary authorities have been actively discussing ways to strengthen the euro’s international role and expand liquidity-provision mechanisms. In September, Christine Lagarde spoke about Europe’s financial sovereignty. On October 21, European Central Bank Executive Board member Philip Lane delivered a speech in Shanghai at an event with the telling title “The Monetary System Beyond the Dollar.”
Lane discussed opportunities to expand the international use of the euro and mechanisms for providing euro liquidity to foreign central banks.
On October 29, Lagarde announced that she would step down as ECB president on February 7, 2027, before the end of her term. She explained the decision as a desire for greater freedom to speak on matters beyond monetary policy.
Could these developments be connected to changing financial relations between Europe and the United States? For now, that remains a hypothesis requiring further evidence.
Permanent dollar swap lines between the Federal Reserve and the ECB remain in place. There is no evidence that Washington has already decided to restrict the European financial system’s access to these facilities.
Nevertheless, the question of Europe’s financial independence is becoming increasingly relevant. If access to dollar liquidity were restricted during a major market shock, the ECB and European banks would find themselves operating under considerably more difficult conditions.
A shortage of dollar funding could trigger stress in currency and credit markets. Under certain circumstances, it could put additional pressure on the euro, increase the cost of imported resources, and complicate the fight against inflation. But such an outcome is by no means inevitable. Much would depend on central bank responses, exchange rates, and the state of global trade.
This is why Fitch’s decision on France is particularly significant. The debt problems of one of Europe’s largest economies are intensifying even before any potential change in the international liquidity system has become a reality.
Now let us turn to Poland.
On October 30, the confrontation surrounding Poland’s Constitutional Tribunal escalated sharply. Following the suspension of the tribunal’s president, Bogdan Święczkowski, and his deputy, substantial police forces appeared outside the building, where protesters had gathered. President Karol Nawrocki interrupted his flight to Senegal and returned to Warsaw.
Prime Minister Donald Tusk’s government describes its actions as an effort to restore the rule of law, while the opposition, led by Jarosław Kaczyński, accuses the authorities of attempting a coup d’état. These are competing political interpretations of events, but the institutional conflict itself is real.
Against this backdrop, Poland’s public finances also deserve attention.
According to official figures, Poland’s government debt, measured under European Union methodology, reached 2.598 trillion zlotys at the end of the second quarter of 2026. The government expects it to rise to 69.3% of GDP in 2027. The draft budget provides for a deficit of up to 281.2 billion zlotys and debt-servicing expenditures of 107 billion zlotys.
On September 18, Moody’s downgraded Poland’s long-term credit rating from A2 to A3, citing large deficits, rising interest expenses, and an expected deterioration in debt indicators.
Yet Poland occupies a distinctive position. Unlike France, it is not a member of the eurozone. It retains its own currency, central bank, and independent monetary policy.
And this raises another hypothesis.
Some members of Poland’s political and financial elite may be seeking to preserve as much independence as possible amid a potential restructuring of Europe’s financial architecture. Poland has traditionally maintained close military and political ties with Washington, while its national currency gives it a degree of room for maneuver.
However, it would be premature to treat the current constitutional crisis as proof that Warsaw is choosing between the dollar-based financial system and its European counterpart. There is no direct evidence of such a connection.
The broader question is whether the national financial strategies of European countries can remain resilient if the eurozone’s problems coincide with a global liquidity crisis.
And now let us return to artificial intelligence.
On November 3, the United States held its midterm elections. Democrats secured majorities in both chambers of Congress. Among the explanations offered by market participants for the renewed sell-off on November 5 were concerns that the political shift could lead to tighter AI regulation and slower data center construction. But this was hardly the only factor. Investors were also worried about the scale of capital expenditures, mounting debt burdens, and the future profitability of the infrastructure being built.
Suppose a further decline in technology valuations coincides with growing sovereign debt problems and mounting stress in the international financial system. The result could be a particularly dangerous combination.
Vast pools of capital belonging to sovereign wealth funds, corporations, and institutional investors would face the threat of substantial losses. At the same time, pressure on government bond markets and bank balance sheets could intensify, making access to liquidity even more important.
Under such circumstances, the position of individual players would depend not only on the value of their assets, but also on their ability to service debt, obtain financing, secure energy supplies, and maintain control over physical infrastructure.
This brings us back to the broader concept of an emerging global economic order in which material infrastructure, energy, logistics, and financial settlement systems become critical sources of influence.
Of course, the current sell-off does not establish that a systemic collapse is inevitable. Financial markets can recover, technologies can find new sources of profitability, and central banks can act to prevent crises from spreading.
But the events of October 30 through November 5 demonstrate how quickly the market valuation of assets once regarded as the foundation of future economic growth can change.
The central question, therefore, is not simply how many trillions of dollars might vanish from financial markets.
The more interesting question is who will end up controlling the real assets if those trillions do disappear.
After all, as history has repeatedly demonstrated, major financial crises often end not with the destruction of wealth, but with its redistribution on a massive scale.
 Yuri Chekalin